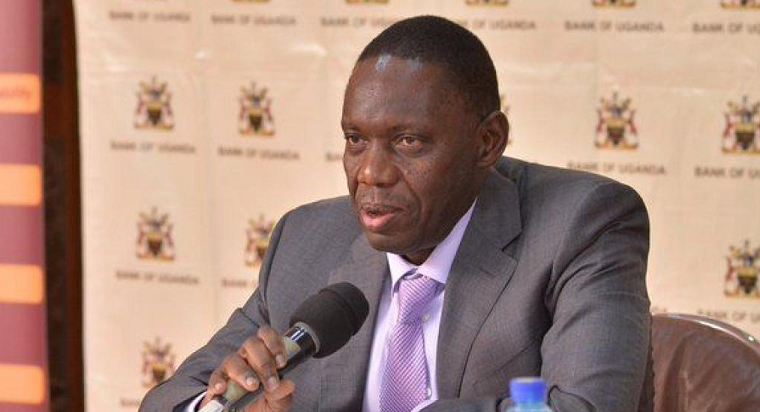


Andrew Nsubuga, Regional Manager for Kampala Metropolitan Area at dfcu Bank
At the beginning of August, dfcu Bank launched the Unsecured Maali Business Loan, targeting formally registered small and medium-sized enterprises (SMEs) that struggle to access credit despite having active businesses and transactional records. Andrew Nsubuga, Regional Manager for Kampala Metropolitan Area at dfcu Bank explains more in this interview with Business Focus. Excerpts:
Q: What gap in Uganda’s SME financing market prompted dfcu to introduce the unsecured Maali Business Loan?
A: dfcu Bank is very passionate about SMEs. In August, we came up with a campaign because we felt we needed to raise the levels of our customers, particularly those in the SME segment. The gap we identified at dfcu is among SMEs that are formally registered but are failing to access financing from financial institutions. These are basically sole proprietorships, partnerships and limited companies. The moment they are registered with us and have transactional businesses, their banking becomes their collateral. We want to support businesses that are operating and have a transactional history but may not have the conventional security required to access financing.
Q: Why has dfcu chosen to offer unsecured financing of up to Shs200 million, and how will the bank manage the associated credit risk?
A: We are looking at a minimum of Ugx10 million up to a maximum of Ugx200 million in unsecured financing. We strive to know our customers. We get to know and understand their location, business location, what the customer needs and what the customer does. Knowing your customer, alongside personalised relationships, will help us minimise the risk.
Q: What has been the response from SMEs since the product was introduced at the beginning of August 2026, and what level of uptake is dfcu targeting?
A: The campaign has received a very good reception. Down in the market and on the streets, all existing customers, as well as new-to-bank customers, are moving into the branches asking about this product. It is a product that has been lacking in the market. Not many have come up to understand why customers have transactional businesses but cannot borrow. So, we came to address that need, and the reception is very massive. We are targeting SMEs that meet the credit lending appraisal criteria of the bank. The uptake is good, and I can assure you the appetite is there and we have the maximum potential to offer credit to our customers.
Q: Many SMEs continue to cite high borrowing costs as a major constraint. How is dfcu ensuring that the Maali loan remains affordable to its target customers?
A: I can assure you this campaign and the product offering are very affordable. We are looking at 27% per annum, which is around 2.25% per month. We have arrangement fees of only 2%, but since the campaign product does not require collateral, we come in with key-man (personal) insurance of 0.5%. We are looking at a maximum repayment period of 12 months, but the customer has the liberty to repay the facility within three to 12 months. The faster you get it, the better. Our turnaround time for this product is just 48 hours. This is a product that is unsecured. We don’t need any collateral. Your banking is your collateral.
Q: The facility requires businesses to have operated for at least three years. Does this leave out promising young businesses, and how does dfcu support enterprises that have not yet reached that threshold?
A: As a bank and with this campaign, we encourage our customers to continue banking regularly. The campaign enables customers to maintain healthy accounts and build strong transactional histories. This will position them for future eligible lending. We are not eliminating those that are less than three years old, but we have to build a journey. We have to start somewhere. There must be a journey. We encourage them to continue banking, maintain healthy accounts and build strong transactional histories. That will position them for future eligible lending.
Q: What safeguards has dfcu put in place to ensure that businesses borrow responsibly and do not take on more debt than their cash flows can support?
A: We have a notion as a bank that responsible borrowing leads to large financing opportunities. We always advise our customers to borrow responsibly and ensure that they live within their means. We monitor their debt service ratios to ensure that we do not strain their businesses. We help customers grow and develop, but we do this while monitoring their debt service ratios. Responsible borrowing also helps prevent customers from diverting funds to projects that have not been planned for. When we promote responsible borrowing, we ensure that our customers are able to manage their debt.
Q: Beyond providing credit, what is dfcu doing to help SMEs improve financial management, governance and business resilience so they can grow sustainably?
A: We have a bouquet of services that we are offering alongside the campaign. First, we are offering free financial literacy sessions. If a customer needs assistance regarding their finances or wants a learning session, it is free of charge. Second, we are offering personalised relationship management. Within this campaign, the customer is king and we strive to offer personalised relationship management. This will help us understand the customer’s business and improve their financial management. Third, we train and encourage our customers to have governance within their businesses and ensure there is business continuity in management and planning. This will keep the business sound and enable customers to grow sustainably.
Q: Looking beyond the Maali Business Loan, what is dfcu’s broader strategy for financing Uganda’s SMEs and supporting private-sector growth?
A: dfcu has a very strong strategy when it comes to SME lending and supporting the private sector. First, we have sector-based lending. We are not lending as a bandwagon. We have sectors in which we operate and in which we need to grow. For example, we have education and health, trade, agriculture, infrastructure and manufacturing. We have tailored ourselves to lend according to a sector-based strategy. This will help us develop many sectors while enabling us to monitor and map our credit cycle. Second, we have digital-based lending. Many customers are now able to obtain SME mobile loans. You don’t have to go to a branch to fill in an application form. You can simply use your phone to apply for an SME mobile loan. Third, we offer asset financing to SMEs. Many customers need transport, trucks and vehicles to transport their products. We also finance machinery. We have trade finance for SMEs, including LPO financing, invoice discounting and warehouse receipting. We also have specialised support programmes such as Women in Business. Many women are accessing credit under the Women in Business programme. We are the anchor and pioneers of Women in Business in the market. We also have institutional partnerships, including partnerships with government, through which we are able to access funds for growth and lend them to customers. Our lending proposition is therefore very broad and rich. It is time for customers to come beyond Maali and consume some of these other products.
Q: How long is the Maali Business Loan campaign running?
A: The campaign started in August. Our prayer is to have it run up to the end of the financial year 2026. We are looking at the campaign running for three months. But dfcu as an institution is good at looking at opportunities, so we might have to run it for the desired time. We are still in the campaign period, and within the three months we feel we can achieve more.
Q: The economy seems to be relatively stable; inflation is under control and the Central Bank Rate is stable. Does this suggest that the campaign is timely?
A: The campaign is timely. The Central Bank Rate is also stable. We are riding on that opportunity to support our customers without charging them and hiking the interest rates. This is the best time for us as a bank to position ourselves to serve our customers, particularly SMEs. It is also the best time for SMEs to come to us, take up this product and get support for their businesses.
Q: Some enterprises may already have loans or other products with dfcu. Would you encourage them to apply for the Maali Business Loan as well?
A: Absolutely. I would encourage them to come for this product. There is no harm in having one, two or three loans, provided you can service them. If you can meet the debt service ratio, there is no harm in consuming a number of products. If you feel that you need this Maali loan to grow and boost your business, we are the chosen opportunity bank for you.
Q: What message do you have for customers or businesses interested in the Maali Business Loan?
A: I want to thank, first and foremost, the customers that we have, both the existing customers and those that we intend to get. Thank you for trusting and believing in dfcu Bank. The message I have is that we are here as a bank to support businesses, transform lives and businesses, and grow businesses. Let us take this opportunity to visit any of our branches or contact us through our call centre. If you are in need of the Maali loan, we are coming on the ground. You can visit our agents. The Maali loan has come to solve many problems within the SME market. It can support working capital, help businesses pay taxes, support expansion and enable them to take up other opportunities and diversify their businesses. The Maali loan is a great option for businesses that need financing within a short period of time.