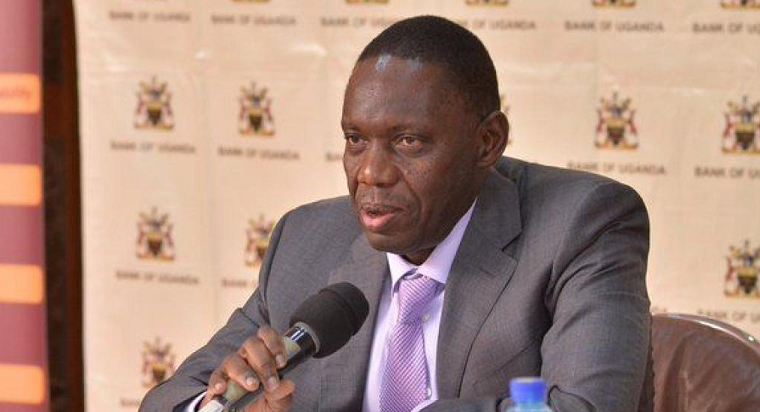


Sebastian Murokozi, Manager Home Loans at dfcu Bank
Uganda’s housing sector was a major focus at the Law and Real Estate Conference organised by Baylor Uganda at Mestil Hotel and Residences on 4 August 2026. Policymakers, developers, legal practitioners, regulators and financial institutions gathered to examine the factors influencing housing access, property ownership and real estate development.
During a panel discussion on Bridging Law and Real Estate for Sustainable Growth, Sebastian Murokozi, Manager Home Loans at dfcu Bank, argued that housing affordability is shaped by far more than the cost of borrowing.
“The affordability of housing is influenced by far more than interest rates,” Murokozi said. “The cost of land, the price of construction, the availability of infrastructure and the efficiency of property administration all ultimately determine whether a household can progress from acquiring land to occupying a completed home.”
For many Ugandan families, homeownership follows a different path from that seen in more mature mortgage markets. Land is often acquired first, while construction takes place gradually as resources become available. Homes are frequently built in phases over several years, financed through savings, business income and personal investments rather than a single mortgage facility.
While homeownership levels remain relatively high, formal housing finance continues to play a limited role in the market. Many households still rely on self-financing and incremental construction to achieve their housing goals.
Housing demand continues to outpace supply. Uganda’s National Population and Housing Census 2024 found that 60% of Ugandans live in informal settlements or inadequate housing conditions, while government estimates place the national housing deficit at more than 2.4 million units. Uganda is estimated to require approximately 300,000 additional housing units annually to keep pace with population growth and urbanisation.

Land values have risen steadily in many urban and peri-urban areas, construction costs remain high and property transactions often involve lengthy verification and documentation processes. These factors increase both the cost of building a home and the time required to complete one.
Mortgage finance presents a further challenge. A significant share of Uganda’s workforce earns income through entrepreneurship, trade, agriculture and self-employment, yet mortgage lending has traditionally been structured around salaried employment and regular monthly income.
Murokozi noted that expanding access to housing finance requires lending models that reflect the realities of today’s economy, where many households generate income from businesses, farming enterprises, professional practice and other non-salaried activities.
He also said that dfcu’s home loans are available for customers purchasing completed homes, completing houses already under construction, renovating existing properties, refinancing existing facilities or unlocking equity from property they already own.
The bank’s Home Loans proposition provides financing of up to 85% of a property’s open market value and offers repayment arrangements designed to accommodate different customer circumstances and income profiles. Home loans are available in both Uganda shillings and US dollars and include mortgage protection cover.
Condominium developments are becoming an increasingly important part of Uganda’s residential landscape as urban populations grow and land becomes more expensive in established urban centres. Higher-density developments are expanding housing options and creating additional pathways to homeownership, particularly in Kampala and surrounding urban areas.
Buyers are paying closer attention to ownership structures, legal compliance, developer track records and project delivery timelines before committing to a purchase. These considerations have become increasingly important as condominium and off-plan developments account for a larger share of the market.
Industry stakeholders at the conference emphasised the importance of title verification, development approvals, contractual review and professional legal advice as part of the home-buying process. Due diligence remains one of the most important safeguards available to prospective homeowners.
Housing supply, infrastructure, land administration, regulation and access to long-term finance all influence whether more Ugandans can successfully achieve homeownership. Progress across these areas will determine how quickly the gap between housing demand and supply can be narrowed.
For financial institutions, developers and policymakers alike, the challenge extends beyond increasing the number of housing units available. The wider goal is creating a housing ecosystem that enables more Ugandans to move from owning land and unfinished structures to owning completed homes.
In that context, the conversation around homeownership is increasingly focused on building practical pathways to ownership in a rapidly changing market.